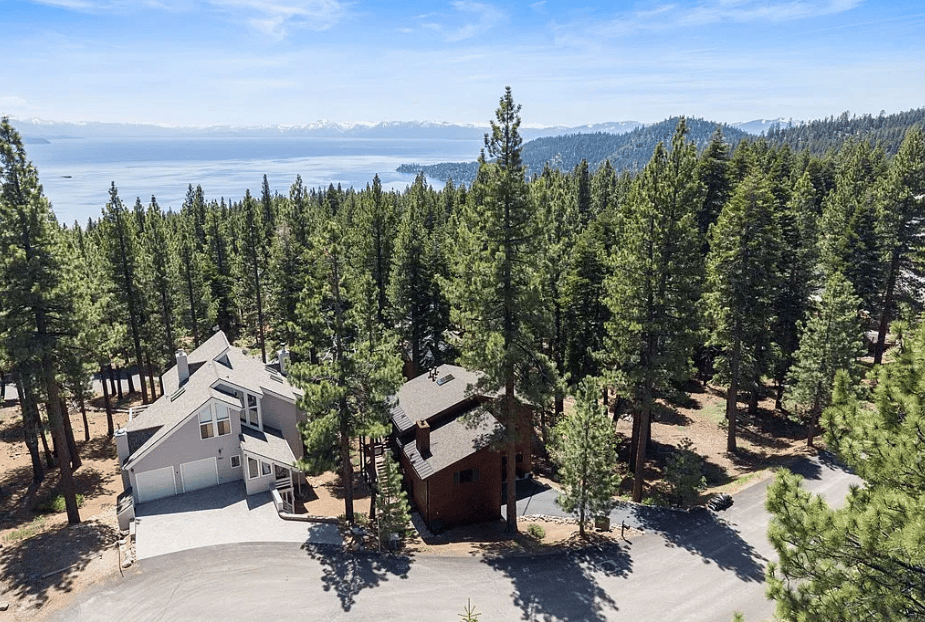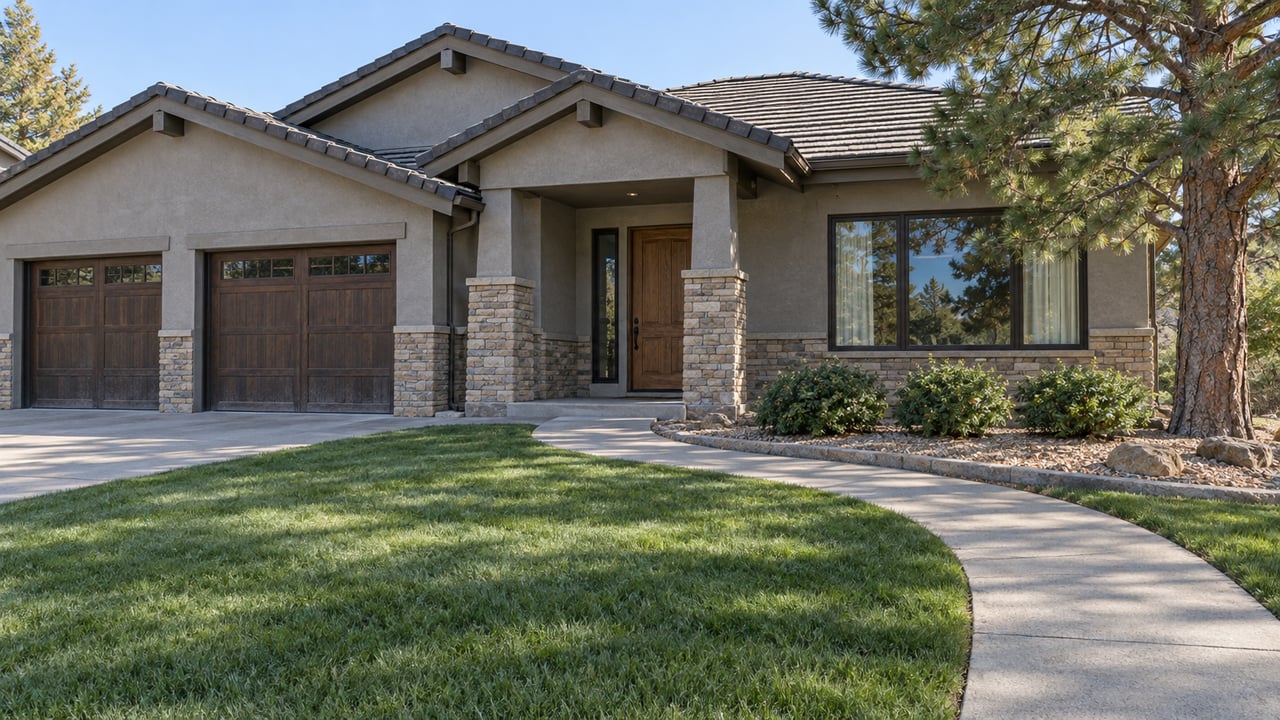
Toll Brothers is advertising a 5.49% 30-year fixed rate (5.76% APR) on select quick move-in homes in Reno, and its Ascente community is where that rate meets the South Reno luxury market. In the last week of October 2026, Freddie Mac's survey put the national average 30-year fixed rate at 7.24%. That's a gap of almost two points, on homes priced at $1 million and up.
The detail that decides who can use the offer is at the bottom of the offer terms. Eligible loan amounts run from $250,000 to $832,750. Ascente's home designs start at $1,049,995. For a buyer weighing an ArrowCreek resale against a new build along Mt. Rose Highway, that gap between the loan cap and the price decides whether the offer helps.
Where the $832,750 Number Comes From
The cap matches the conforming loan limit exactly. FHFA's 2026 county-level list sets the one-unit limit for Washoe County at $832,750, the same as the national baseline FHFA announced for 2026. A loan above that amount is a jumbo loan, and the builder's rate doesn't cover it.
The offer also says buyers need "as little as 10% down." On a $555,556 home, the price Toll uses in its own example, 10% down produces a $500,000 loan, well under the cap. At Ascente's prices, 10% down produces a loan above $832,750 on every home listed. The real minimum down payment is the price minus $832,750.
What the Cap Means at Ascente's Actual Prices
Here is that math for Ascente's lowest starting price and its three quick move-in homes, using Toll's listed prices.
| Home | Listed price | Cash needed to keep the loan at $832,750 | Share of price |
|---|---|---|---|
| Brunello, Copper Rock Collection, base price | $1,049,995 | $217,245 | About 21% |
| Royce Elite Modern Ranch, Copper Crest Trl | $1,274,000 | $441,250 | About 35% |
| Royce Modern Ranch, Copper Valley Ct | $1,300,000 | $467,250 | About 36% |
| Hendrix Air Mountain Modern, Viewline Ct | $1,875,000 | $1,042,250 | About 56% |
The Brunello figure is a starting price before design studio selections, so any upgrades add to the cash needed. Buyers pick finishes at the Toll Brothers Design Studio, and every dollar of options raises the price while the loan cap stays put.
So at this price point, the 5.49% rate goes to buyers with enough cash to keep the loan under the cap. It doesn't help buyers stretching to reach a $1.2 million home with a small down payment.
What the Rate Is Worth on a Maxed-Out Loan
For the buyer who does have the cash, the savings are large. Toll's fine print gives a payment factor of $5.67 per $1,000 financed. On a full $832,750 loan, that comes to about $4,722 a month in principal and interest.
The same loan at Freddie Mac's 7.24% weekly average works out to roughly $5,675 a month. That's a difference of about $950 a month, or more than $11,000 a year, before taxes, insurance and HOA dues. Freddie Mac's figure is a national average rather than a quote, so treat this as a rough comparison of scale.
The cap also limits the savings. Every buyer who qualifies ends up with a loan of no more than $832,750, so the monthly benefit is about the same on the Brunello as on the Hendrix. On the more expensive homes, the buyer brings more cash but saves the same amount each month.
Above the Cap, the Jumbo Market Is Slightly Cheaper Right Now
A buyer who can't or won't put that much down moves into jumbo financing. Right now, that market doesn't charge extra for the larger loan.
The Mortgage Bankers Association's weekly survey for the week ending October 23, 2026 reported an average contract rate of 7.28% on 30-year fixed jumbo loans, which are balances above $832,750. Conforming balances averaged 7.37%. Jumbo points were also slightly lower, 0.64 against 0.76 for 80% loan-to-value loans.
That fits the larger point. At the conforming limit, the market isn't penalizing large loans this fall, and Toll's offer covers one band of loan sizes. An ArrowCreek resale buyer financing $1 million with a jumbo loan and an Ascente buyer financing $1 million with a jumbo loan start from about the same market rate. The 5.49% only changes the comparison for the buyer who keeps the loan at or under $832,750.
The Calendar Narrows It Further
The offer has a deadline. Under Toll's posted offer terms, agreements must be signed on or after October 8, 2026, and the home must close by January 8, 2027. From early November, that leaves about two months.
Toll lists the Hendrix on Viewline Ct as move-in ready. It lists the Royce on Copper Valley Ct for January 2027 and the Royce Elite on Copper Crest Trl for February 2027. The offer applies to select quick move-in homes that can close by January 8, so a February completion date falls outside it as written. The home that can most clearly close in time is also the one that needs more than $1 million down to stay inside the cap.
Several other conditions apply:
- Primary residences only, so second-home buyers aren't eligible.
- FHA and VA loans aren't eligible.
- Credit scores under 740 add costs that may raise the APR.
- The rate must be locked through Toll Brothers Mortgage Company and can't be combined with other offers.
- Toll can change or withdraw the offer at any time.
The terms also say incentives are subject to maximum interested-party contribution limits based on loan program and down payment. This is general information, not financial or lending advice. Any buyer considering the offer should confirm eligibility, costs and timing with the lender and their own financial advisor.
Why a Builder Offers This in a Tight Resale Market
On the resale side, sellers this fall aren't giving up much. Sierra Nevada REALTORS' September 2026 report for Washoe County shows a $595,000 median sale price, up 9.7% from a year earlier. It also shows a median of 28 days to contract, sellers receiving 98.7% of list price, and 2.5 months of supply. Active listings were 1,196, down 19.9% year over year. Those figures cover the whole county and three residential property types, so they describe the overall market rather than ArrowCreek in particular.
With inventory that tight, a resale seller has little reason to cut the price. A builder with finished homes to close faces a different calculation, and a rate offer protects the listed price while still lowering the buyer's monthly payment. By capping the offer at the conforming limit, Toll can likely finance those loans on standard conforming terms, which may explain why the cap sits exactly at $832,750. The fine print supports the cap but doesn't state the reason, so treat that explanation as a reasonable reading.
Ascente has also been in the works for a long time. Washoe County's planning case TM16-009, laid out in the 2017 Planning Commission staff presentation, was approved in 2017 for 225 single-family lots on a 225-acre site south of Mount Rose Highway and Fawn Lane, east of Callahan Road, with 80 acres of open space. Final maps were recorded in 2022 and 2024, according to a 2024 county staff report. A 2026 county staff report addressed the last remaining development area at Desert Ridge Drive and Ascente Crest Trail. That report describes the next map as covering custom lots, so part of the community is still unbuilt.
Quick Answers
Can a buyer use the 5.49% rate on a second home at Ascente? No. The terms limit it to primary residences.
Does the offer apply to Ascente's design-and-build homes or to all quick move-in homes? The offer applies to select quick move-in homes that can close by January 8, 2027. The sales team can say which homes qualify.
Is the cap tied to Washoe County specifically? The $832,750 cap matches Washoe County's 2026 one-unit conforming limit on FHFA's list.
If you're comparing an ArrowCreek resale with new construction up Mt. Rose Highway, the right answer depends on how much cash you can put down and when you need to close. Jodi Kruse spent years in lending before real estate, and she can run your down-payment, loan size and timing numbers on both options side by side before you sign a contract. Reno's Realty Group can help you get the comparison right. Schedule Your Free Concierge Consultation.